Facing Foreclosure in Portland?
You Have More Options Than You Think
Falling behind doesn't make you a bad person, and you don't have to figure this out alone. Here's a calm, plain look at your choices, including selling your house.
This Page Is for You If…
How Foreclosure Generally Works in Oregon
This is a general overview, not legal advice. Your own situation may be different.
Most home foreclosures in Oregon are handled outside of court, through what's called a trustee's sale. The process usually starts after a homeowner misses payments. The lender sends letters, and then formal notices, such as a notice of default. If the loan isn't brought current or paid off, the house can be sold at a trustee's sale.
How long each step takes varies from case to case. It depends on your loan, your lender, and what's happened so far.
Two things help most people: read every notice carefully, and get help early. The earlier you look at your options, the more of them you're likely to have. If you're not sure what a letter means, a housing counselor or an attorney can explain it.
Your Options, Honestly Compared
Selling to us is only one option, and it isn't right for everyone. Here are the main paths people take, with the good and the hard parts of each.
Catching up (reinstatement). You pay the missed payments plus fees to bring the loan current. Pro: you keep your home. Con: you need the money, often all at once.
Loan modification or forbearance. Your lender changes your loan terms or pauses payments for a while. Pro: you may keep your home with a payment you can afford. Con: it needs lender approval, and it can take time and lots of paperwork.
Free help from a HUD-approved housing counselor. A counselor can review your situation and help you talk to your lender. Pro: it's often free, and they work for you. Con: they can't make your lender say yes.
A short sale. If you owe more than the house is worth, the lender may agree to accept less than the full balance. Pro: it can avoid a completed foreclosure. Con: it needs lender approval, and it often takes a long time.
A traditional listing. If there's enough time and equity, listing with an agent may get you the highest price. Con: showings, repairs, and waiting on a buyer's loan.
A fast cash sale. You sell to a cash buyer, like us, and the loan is paid off at closing. Pro: speed, no repairs, and a closing date you choose. Con: you'll likely get less than a full market price.
If another option looks better for you, Nick will tell you.
How a Fast Cash Sale Can Help
Can selling stop foreclosure in Oregon? Here's the honest answer: if your house sells and your loan is paid off before the foreclosure sale, the foreclosure ends. We can't promise that will happen in every case, but a quick sale gives you a real chance at it.
Here's how the money works. At closing, the licensed Oregon title company uses the sale money to pay off your mortgage and any other liens. If there's equity left over, that money goes to you.
Selling is also generally less damaging to your credit than a completed foreclosure. Everyone's credit is different, so it's a good idea to ask a credit counselor how it may affect yours.
You pick a closing date that works for you. You can see how we figure our number on our sell for cash page.
Real People.
Real Results.
Nick saved our house from foreclosure, I'm so so grateful. We had 3 weeks until we lost our house to auction and so selling the traditional way wasn't possible. We needed to move fast and Nick did just that. He's honest, seems to care, and did everything he said he was going to do. Thank you Nick!
Why Nick Is Comfortable With Hard Situations
Before he started buying houses, Nick Hooyman was a mortgage broker. He understands how loans, payoffs, and lenders work, so the letters you're getting won't surprise him. He also earned a law degree from The George Washington University and a Master of Laws in tax from NYU. That doesn't make him your lawyer, but it helps him explain each step in plain words.
Nick treats every call as private. There's no pressure and no judgment. He may also be able to help cover your moving costs, so you can start fresh. You can read more about Nick and why he does this work.
Free Help You Should Know About
You don't have to go through this alone, and some of the best help costs nothing.
HUD-approved housing counselors. These counselors can review your situation, explain your options, and help you talk with your lender. You can find a HUD-approved housing counselor near you.
Oregon Housing and Community Services. The state shares information about mortgage payment help and foreclosure prevention for Oregon homeowners. See Oregon's foreclosure prevention resources.
It's worth talking to one of these resources even if you end up selling to us.
Compare Your Choices
Sell in 3 Simple Steps
Tell Us About Your Home
Fill out our quick form or call us. Takes less than 5 minutes and there's zero obligation to proceed.
Receive Your Cash Offer
Within 24 hours you get a fair written cash offer. We walk you through every number — no surprises, ever.
Pick Your Closing Date
Accept and choose when to close. In many cases as fast as 7 days, or whenever works best for your situation.
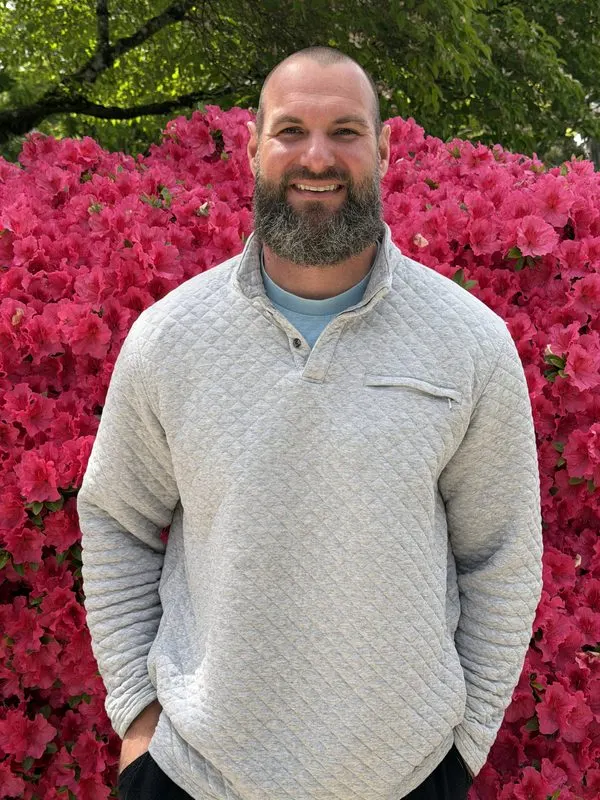
A Local Buyer You Can Call
Nick Hooyman has worked in real estate since 2005 — as a mortgage broker, a licensed agent, and now a full-time investor. He also earned a law degree from The George Washington University and a Master of Laws in tax from NYU. That training doesn't replace your own lawyer or tax advisor, but it helps him explain each step in plain words.
More About Nick →Common Questions
This page is general information, not legal or financial advice. Talk to an attorney or a HUD-approved housing counselor about your specific situation.
Areas We Serve
Other Ways We Help
Ready to Talk?
Get Your Free Offer.
Tell us about your property and get a fair, no-obligation cash offer within 24 hours. Prefer to talk? Call or text (503) 850-2565.